Looking after the family jewels

Independent Contributor
In my last article “Growing the Family Farm” I showed how using debt constructively over time can grow a business without making any significant profit….this led to some queries on why?….or what next?….how does it look in practical succession planning?
Succession planning is a trendy term nowadays, but there certainly isn’t a one size fits all strategy, and success isn’t only measured financially, open to debate, but the key metric is family members and ‘in-laws’ all still talking to each other. Ultimately this relies on shared values, communication and the actual ‘succession planning’ being an ingrained business strategy.
I’ve been through 2 divorces and miraculously still have the original farm I returned too after 10 years shearing sheep. A key factor here my parent’s early family trust set up, and now approaching 55, and my first 2 kids approaching 30 I’m actively encouraging them into business….very gently….as somewhere between Boomers, Gen X, Y & Z risk aversity, and an allergy to debt crept in. Which itself is something of an oxymoron with most western democratic governments now carrying $40,000 – 100,000 of debt for every man woman and child in their countries.
The last article showed a table of how I’ve grown what I inherited over the last 26 years, and am oddly proud that I’ve made no significant profit or paid off any debt. It would actually appear I’ve come from the Trump school of economics. The only reason it works and the same reason America isn’t broke, and Australia and NZ don’t need to get too worried about their ‘debt mountains’ is the fact that highly leveraged capital intense businesses enjoy the benefit of inflation over time (Capital appreciation or CAGR) this dilutes the underlying debt which isn’t affected by inflation at all…..if the business you are running can pay the interest, why pay principal, inflation dilutes it faster than you can pay it (explained further in “Why I love Agriculture”)
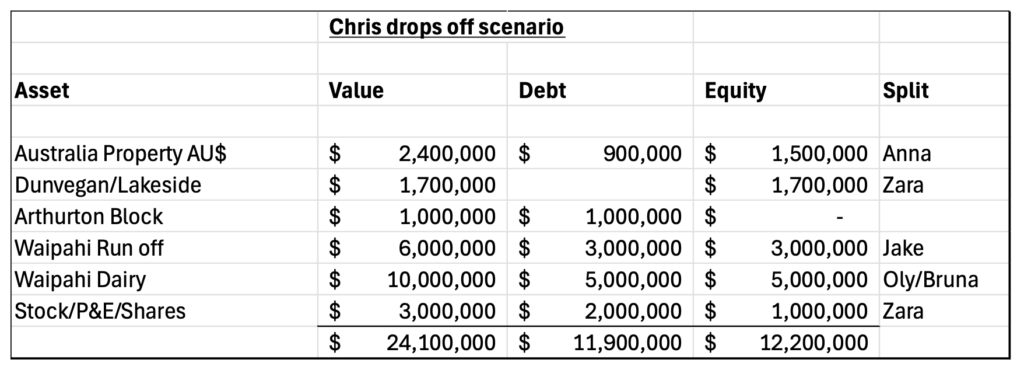
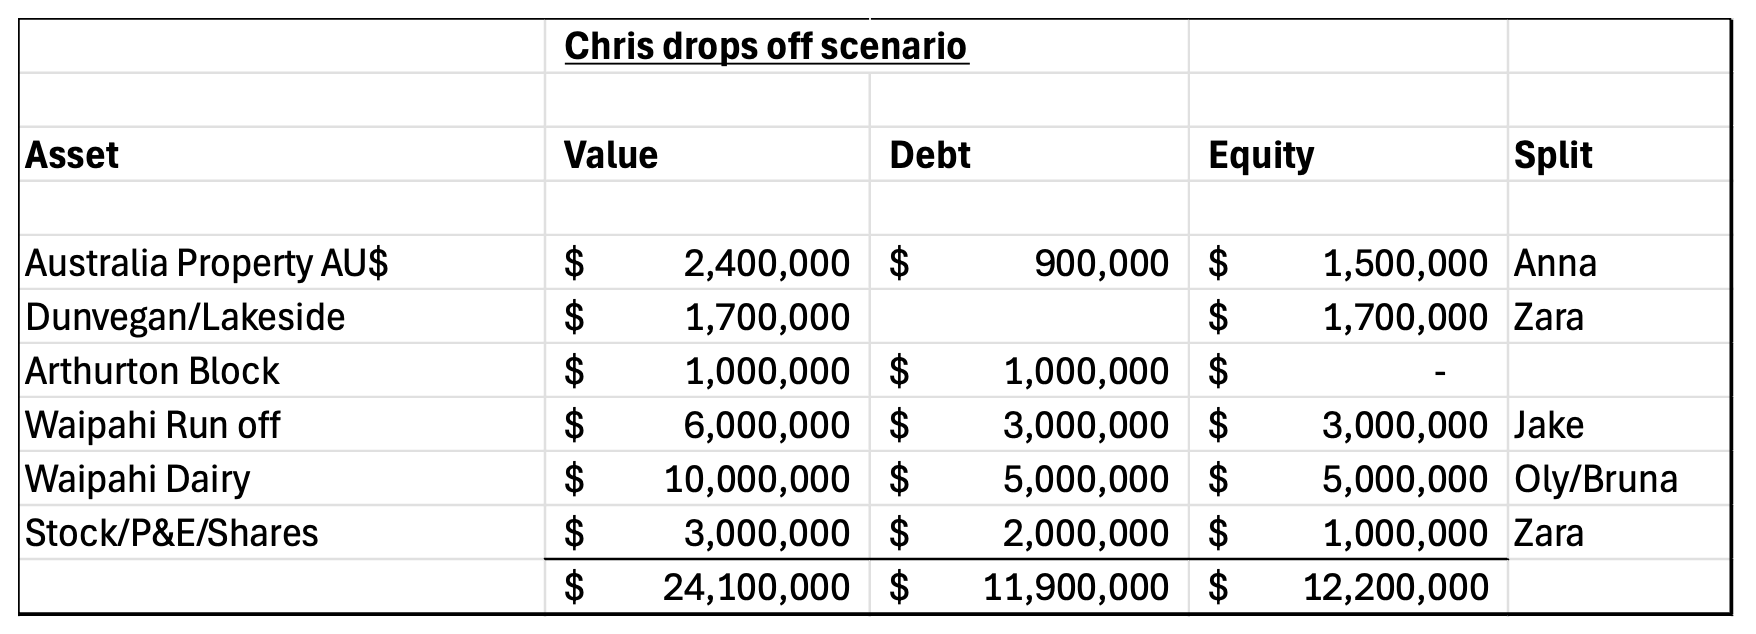
So, from the $4 million asset with $2 million debt in 2000 to $24 million in assets with $12 million debt in 2026, my sister who is the other trustee of my family trust, quite rightly queried what happens if something happens to me, ie key person risk. And it sounds crazy that much debt, a third wife….4 kids….high blood pressure and an enlarged prostate….
So I made up the table below which I will update annually as I attempt to encourage my older 2 into business (not that difficult, but the debt aversion will take time)
With the housing market crashing and all the doom, gloom and wars going on, it may seem logical to consolidate and reduce debt…..bollocks…..high inflation and reasonable interest rates is the perfect environment for mine and Trumps economic theory to continue.
This is a topic 90% of people avoid or leave too late, I plan on doubling this with all stakeholders in the next 10 years and living till I’m 100….but it’s important to have a plan B. And communicate to some level….publishing isn’t necessary 😉
Next article looks at doing this practically with outside help to protect the most important thing to me….internal stakeholder relationships. Look out for Looking after the Family Jewels 2…..